RBA Lifts the Cash Rate to 4.60%. What Happens Now?
By Leigh Martinuzzi of Martinuzzi Group – eXp Realty | Sunshine Coast Real Estate
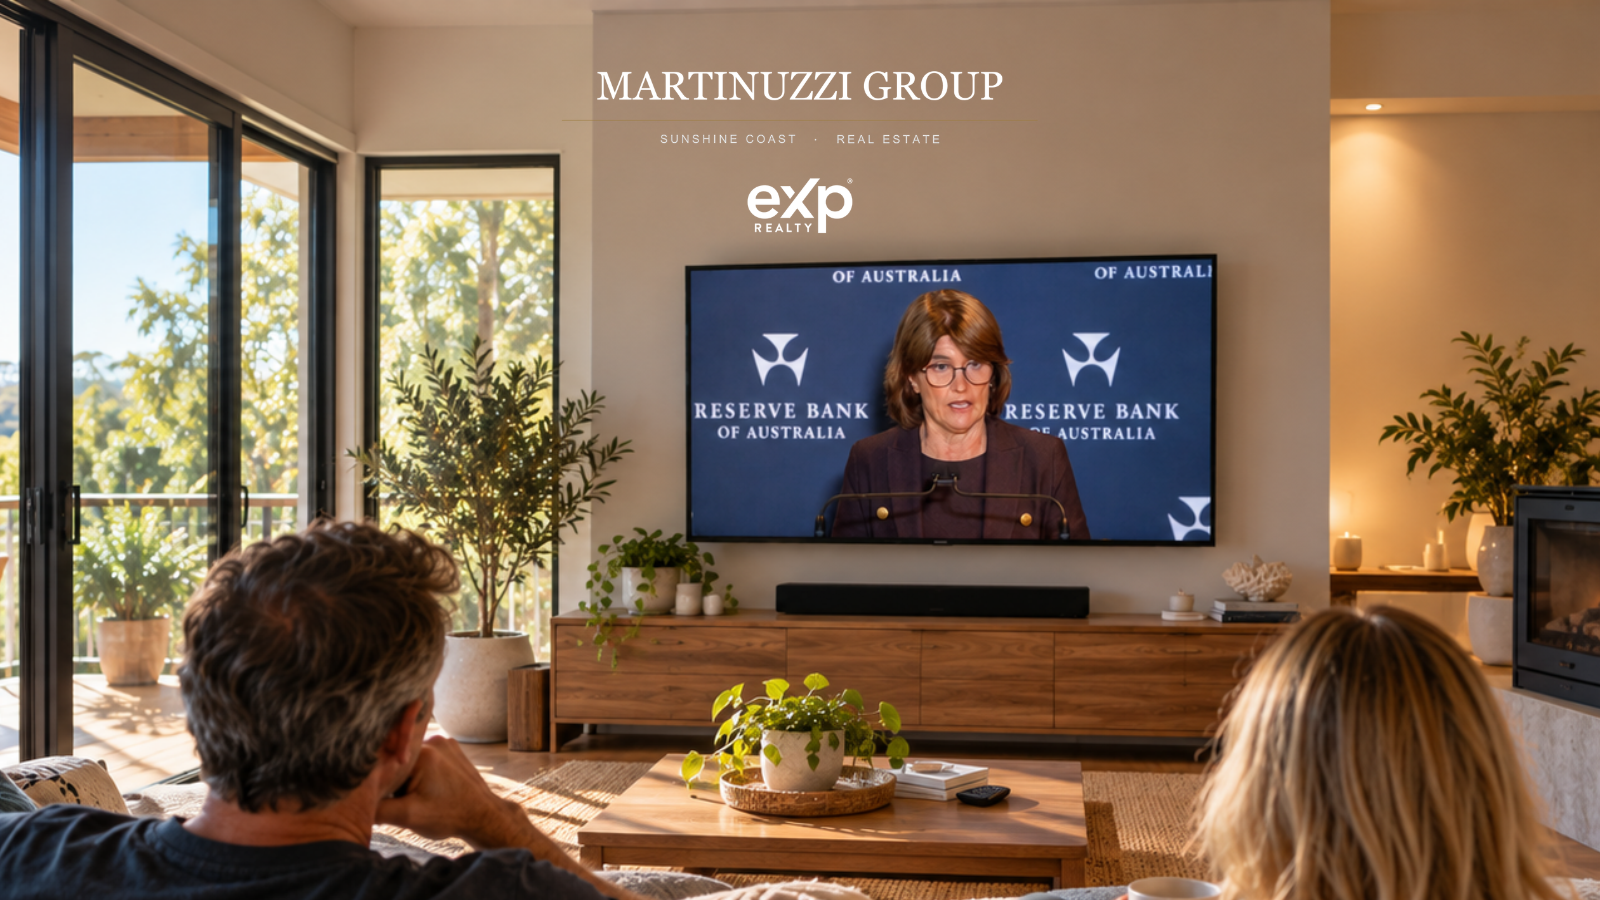
It has been a big week for anyone with a mortgage or anyone thinking about buying or selling. On Tuesday 29 September, the Reserve Bank lifted the cash rate by 25 basis points to 4.60%. This is the fourth rise this year, and it takes the cash rate to its highest level in about 15 years.
The day after, the latest inflation figures were released. They weren’t the news many households were hoping for.
My view is that we’re probably not at the peak of interest rates yet. I’m going to be straight with you about what that means. The most important thing I want you to take from this week, though, is simple: don’t panic. Panicking won’t help you make a better decision, but a clear strategy will.
Why the RBA Raised Rates Again
The RBA’s reasoning was simple. The Board said inflation is still too high and that financial conditions need to tighten further to bring it back to target within a reasonable time. The decision was unanimous, and the Board made it clear it is prepared to lift rates again if needed.
Rates rose in February, March and May, then held for two meetings. With this latest move, the cash rate is now a full percentage point higher than it was at the start of the year.
I’ll be honest. Raising rates seems to be the only lever the RBA knows how to pull, and I’m not convinced it will control inflation on its own. Government spending is fairly high, and it’s hard to see rate rises doing all the work while that continues. KPMG’s chief economist, Brendan Rynne, made a similar point this week. He said monetary and fiscal policy need to work together to bring inflation back to target.
My other concern is who carries the cost. Rate rises hit mortgage holders first and hardest. That includes young people who’ve just bought their first home, and families five or six years into their loan, all at a time when the cost of living is already very high. Mortgage holders aren’t the majority of the Australian population, so this group is carrying a heavy share of the burden. That’s another reason I don’t think this will necessarily have the effect the RBA wants.
Inflation Rose to 4% in August
On Wednesday 30 September, the Australian Bureau of Statistics released its monthly figures. Headline inflation rose to 4.0% in the year to August, up from 3.5% in July. Housing was the biggest contributor. New dwelling prices rose 5.4% over the year as builders passed on higher costs for materials and labour. Fuel prices also rose sharply.
There’s one detail worth knowing. The RBA pays closest attention to a measure called trimmed mean inflation, which leaves out the most volatile price changes. That figure held steady at 3.6% for the third month in a row, and the headline figure came in slightly below what economists had forecast.
Because of that, money markets have lowered the chance of a November rise to around 20%, according to the ABC. Not everyone agrees. Westpac’s Luci Ellis still expects another increase within a couple of months unless energy costs ease. EY’s Paula Gadsby has said the Board may need to raise rates again before the end of the year.
I’m with the economists who think another rise is still a real possibility. It could come when the RBA meets in early November, or when it meets again in February. Either way, it’s worth keeping an eye on.
Higher Rates Will Slow the Market Further
We’ve already seen what the first three rises did. According to Cotality’s Home Value Index, released today, national dwelling values fell 1.1% in September. That’s the sixth monthly fall in a row, and values are now 5.2% below their March peak. Brisbane had the steepest fall of the capital cities, at 1.5%.
Fewer homes are selling, too. Cotality estimates that home sales nationally over the past three months were about 19% lower than a year earlier. In the capital cities, homes now take a median of 39 days to sell, compared with 23 days a year ago.
In my view, this fourth rise will definitely slow the market further. Fewer people can borrow what they could a year ago, and that flows straight through to buyer numbers, enquiries and demand across the board. Cotality’s research director, Tim Lawless, expects conditions to stay under downward pressure in the months ahead. He also expects a resilient jobs market and low levels of new housing to help prevent a sharp correction.
What It Means for Homeowners
If you have a mortgage, each rise adds to your repayments. The ACTU estimates that this year’s four increases add around $460 a month to the cost of an average mortgage. Your own figure will depend on your loan size and your lender.
If you haven’t reviewed your home loan for a while, now is a good time to talk to your broker or lender. Your current rate may no longer be competitive.
If you’re thinking about upgrading or downsizing in the next year, find out where your property sits today. When the market shifts, it affects both the home you sell and the home you buy, so it pays to understand both sides before you commit.
What It Means for Sellers
When people can borrow less, there are fewer buyers. That usually means fewer enquiries, smaller crowds at open homes and homes taking longer to sell. Buyers also have more choice and less urgency, which gives them more room to negotiate.
That doesn’t mean you can’t get a good result. Plenty of people are still buying and selling in markets like this. What changes is how much your strategy matters.
Pricing well from the start is far more important now than it was when the market was rising. A home that sits on the market at a hopeful price can lose momentum, and getting that momentum back is hard. Presentation, choosing the right sale method and careful negotiation all make a real difference when buyers are being selective. Stay aware of what’s happening in the market, and choose a strategy that will actually help you get the result you want.
What It Means for Buyers
If you got pre-approval earlier in the year, check it again. A higher cash rate means you can borrow less. Lenders also test whether you could afford the loan at a rate higher than the one you’ll actually pay.
On the positive side, you’re likely to have more choice, more time and more room to negotiate than buyers had 12 months ago. Plan for the possibility of another rise, and don’t stretch yourself too far just to secure a property.
The Sunshine Coast Angle
Regional markets have held up better than the capital cities overall. Cotality’s latest figures show regional dwelling values are up 5.6% over the past year, while the combined capitals are down 1.8%.
The Sunshine Coast is one of the country’s higher-priced regional markets, though. Where prices are higher, changes in borrowing capacity can have a bigger effect on how many buyers can afford a particular property. That’s why I wouldn’t assume national averages tell you what’s happening here.
In our part of the hinterland, including Palmwoods, Woombye, Nambour and the surrounding areas, conditions can vary a lot by price point, property type and street. Your local comparable sales, and the homes competing with yours right now, will tell you far more than a national headline.
Don’t Panic
It’s natural to feel uneasy when rates go up and headlines turn negative. I understand that. But panicking won’t get you anywhere. Rushed decisions made out of fear rarely lead to good outcomes, whether that means selling in a hurry, pulling out of a purchase or freezing altogether.
Markets like this one have come and gone before, and people still buy, sell and move forward with their lives. Those who do well are usually the ones who stay calm, get good information and make a plan that suits their own situation rather than reacting to the news of the week.
So be aware, be realistic and be prepared. Just don’t panic.
Thinking About Your Next Move?
If you’re wondering what this rate rise means for your property, it may be worth getting an updated opinion. A short conversation can help you see where your home sits in today’s market and which strategy suits your timing and goals. Feel free to reach out anytime. We’re always happy to have a no-pressure chat.
Get in touch with us today and and let’s give you fantastic results that you deserve.
SUBSCRIBE to stay up to date with all the latest property insights and news.
Click Here to Subscribe
The Sunshine Coast Seller’s Guide to Choosing the Right Agent
Get Your Free Guide Here
Just Listed Your Home? Here’s What Happens Next (And How to Get Ready for a Great Result)
Download the Guide Here
Sources: Property Update; Domain House Price Report (June 2026) and Matching Demand Report (September 2026); Cotality Home Value Index and Monthly Housing Chart Pack (September 2026); Reserve Bank of Australia.